quantsys
A rules-based trading system for Indian stocks
- My role
- Research, design and development
- Made for
- A personal research project in rules-based trading. It is not a product and not investment advice.
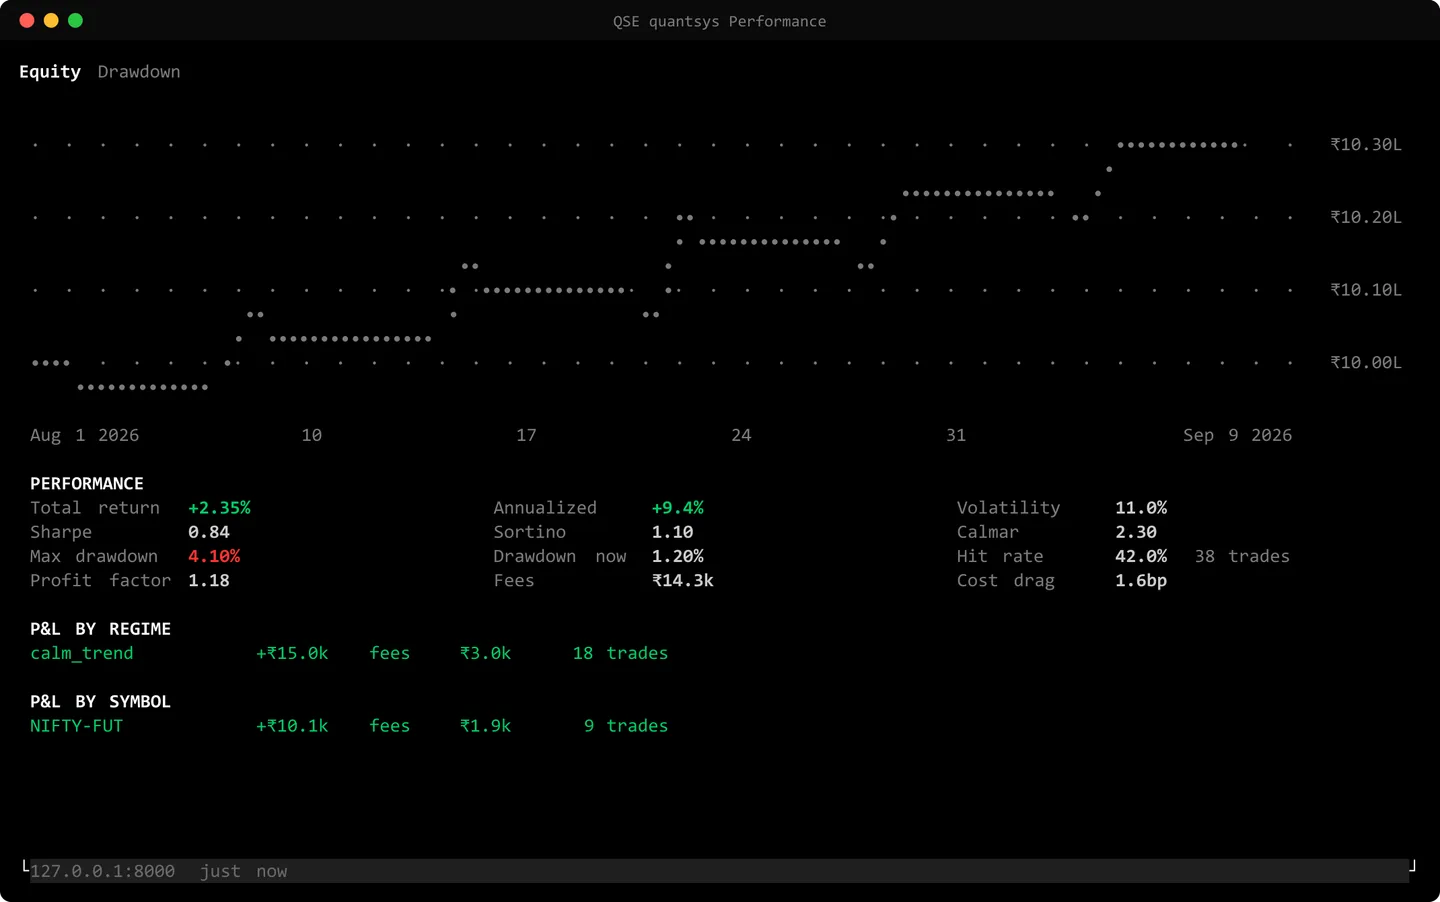
Not investment advice. Every screen here shows demo data, not real trades.
What it is
quantsys trades the Indian stock market (NSE) by fixed rules instead of gut feeling. It follows 48 large companies and the NIFTY and BANKNIFTY index futures.
The same decision engine runs the tests on past data, the paper trading and live trading, so a result from one holds for the others. Every decision keeps a full record of why it was made and which risk limits changed it.
So far, ten years of tests (2016 to 2026) found no rule that beats simply holding the index after costs. That is why it trades only on paper, in a study that has run since July 2026.
What it does
One engine for every mode
Tests on past data, paper trading and live trading all run the same decision code.
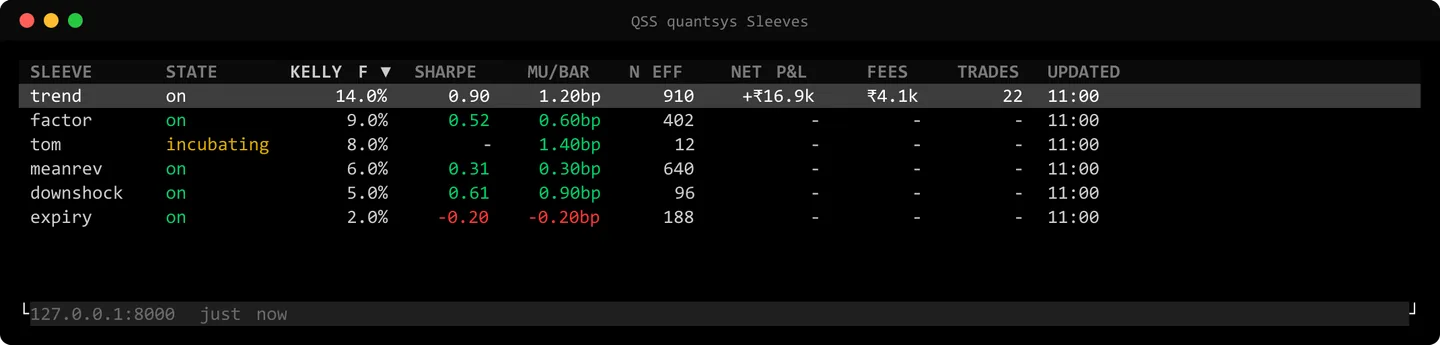
Several strategies side by side
Trend following, pairs of similar stocks, momentum, month-end and expiry-week patterns, each given money according to its measured edge.
Risk limits come first
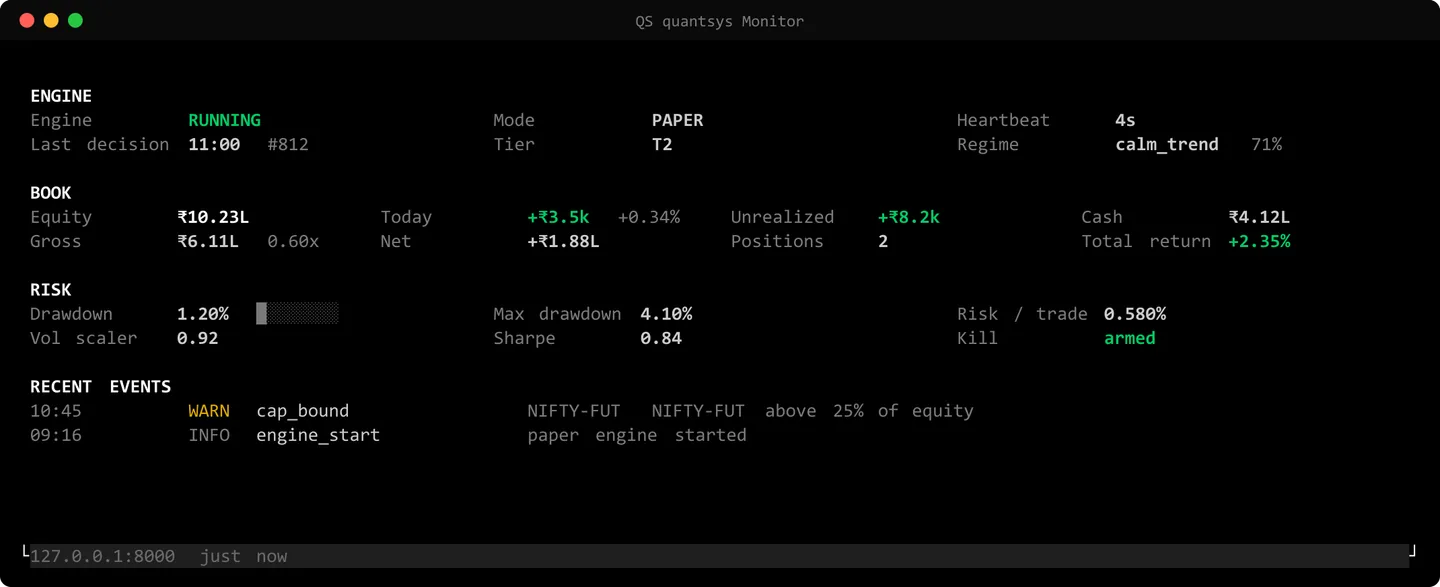
Each trade risks at most 0.6% of the account, trading stops for the day after a 2.5% loss, and a 20% fall stops everything until a person restarts it.
A reason for everything
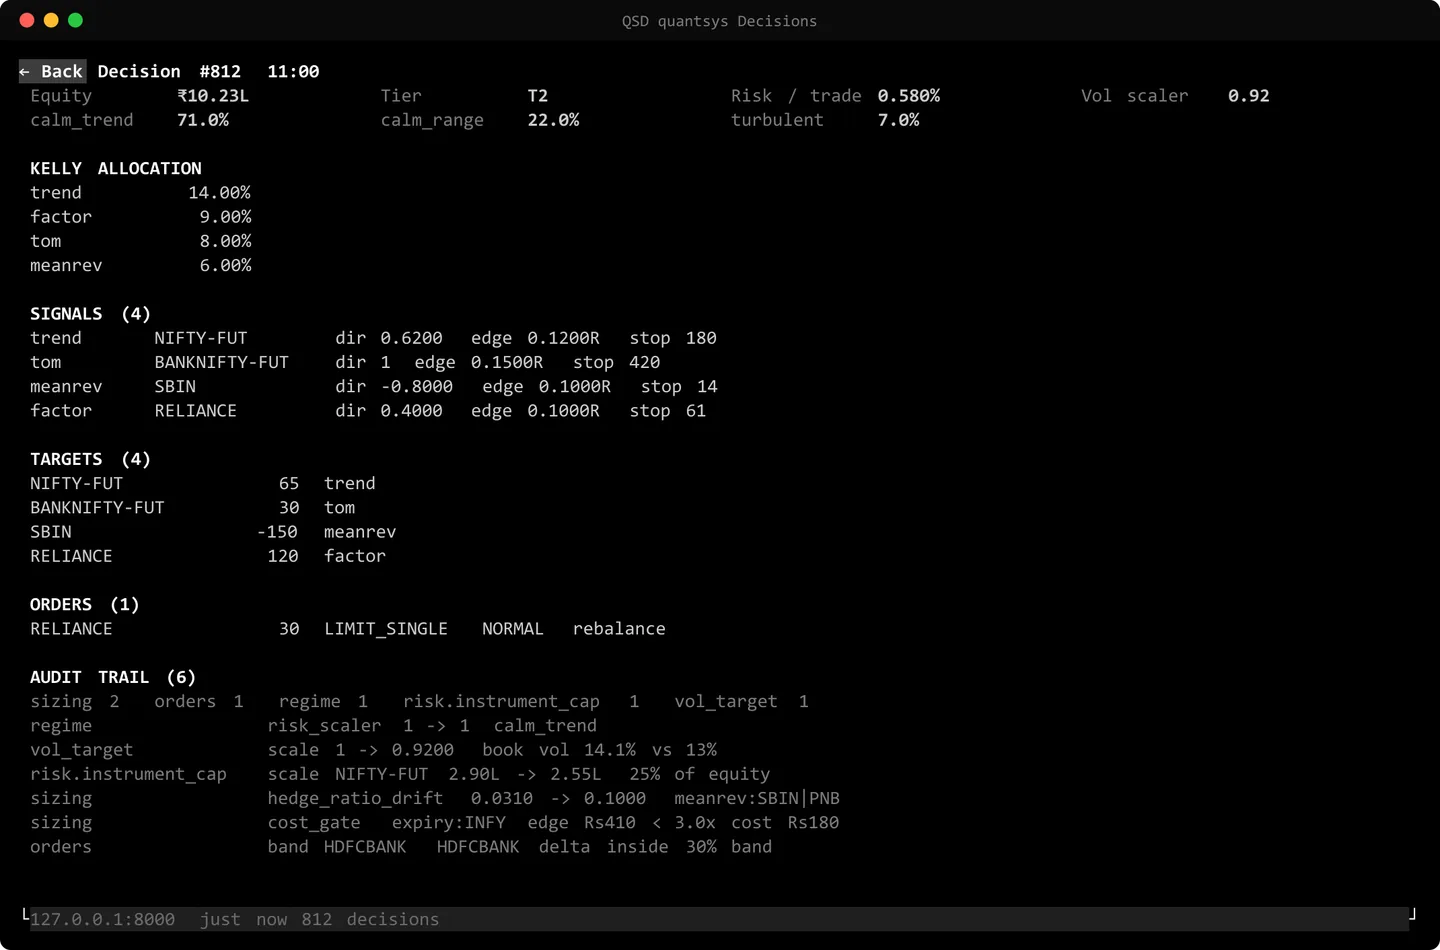
Every blocked trade and every change in size goes into an audit trail, so any decision can be explained later.
Live trading stays locked
Real money is only possible after a strategy passes strict statistical tests on real data, the broker is connected and the operator signs in again.
A terminal view
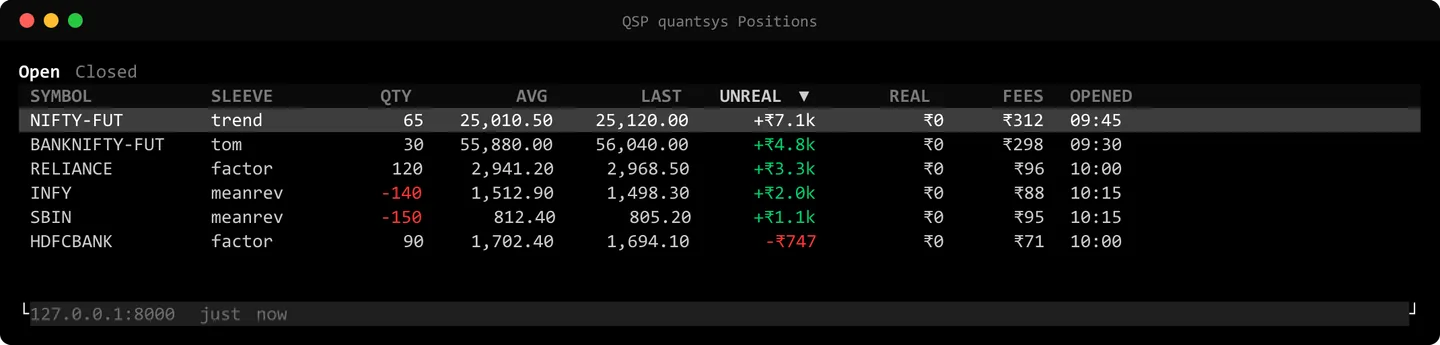
A read-only monitor shows decisions, positions, risk and performance, each opened with a short code, like a trading terminal.
Screenshots
The terminal screens are rendered from demo data.
How it is built
The engine and the research tools are written in Python with NumPy, pandas, SciPy and statsmodels. A FastAPI service and a Next.js dashboard sit on top, backed by PostgreSQL with TimescaleDB, and Redis.
It connects to the Angel One SmartAPI broker, and every setting lives in one configuration file.
- Python
- NumPy
- pandas
- FastAPI
- PostgreSQL
- TimescaleDB
- Redis
- Next.js
- TypeScript
- Docker